General Liability Insurance
General liability insurance protects your business when a third party — a customer, visitor, or vendor —
suffers bodily injury or property damage connected to your operations, products, or premises. It also
covers personal and advertising injury, such as libel or copyright claims. It helps pay medical costs,
legal defense, settlements, and court-awarded damages. Often the first policy a business buys, it's
foundational cover for the everyday risks of dealing with the public
Commercial Auto Insurance
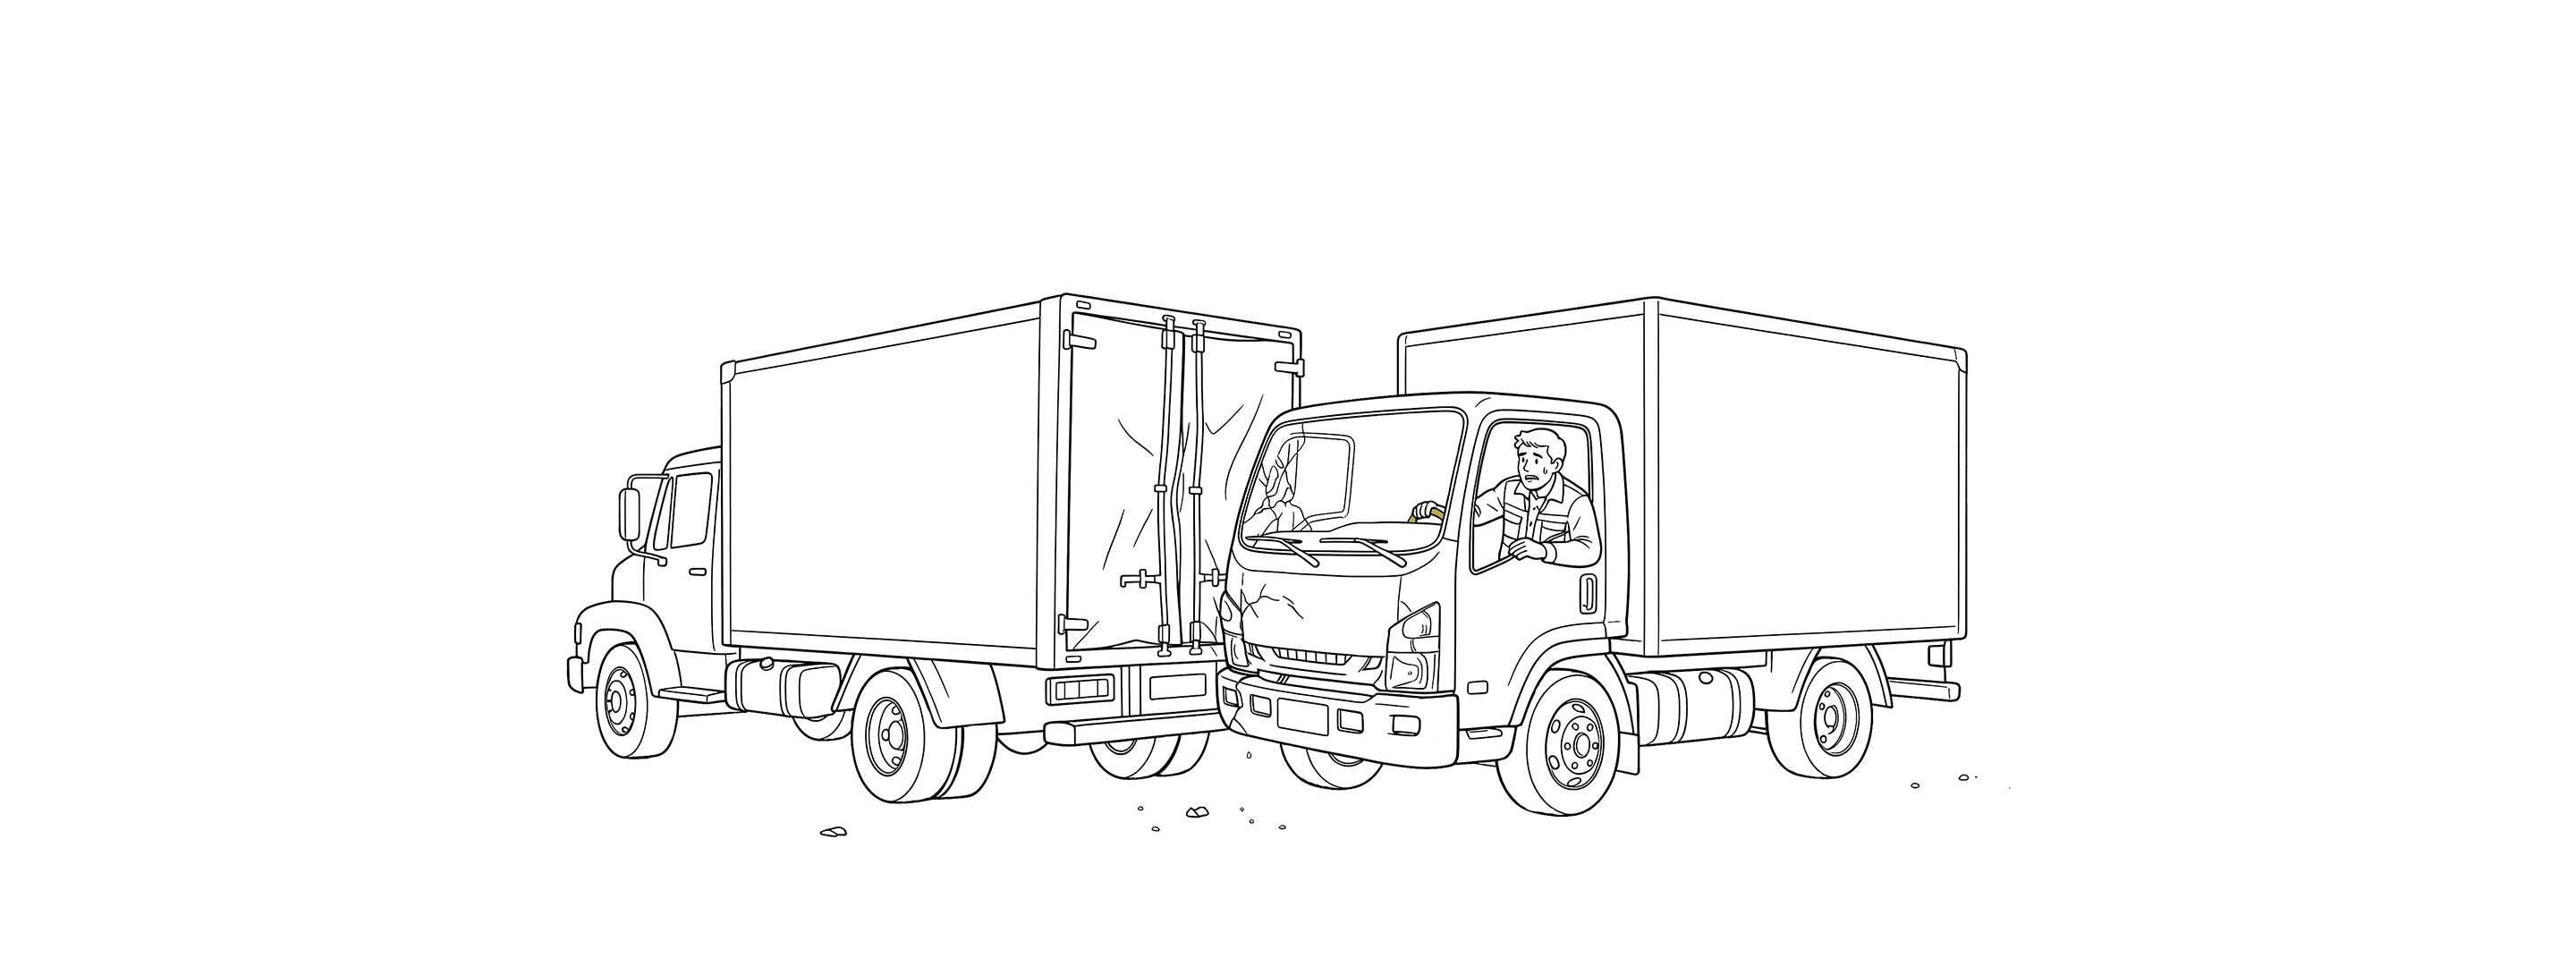
Commercial auto insurance covers the cars, vans, and trucks your business owns or operates. It pays to
repair or replace a company vehicle damaged in an accident, vandalized, or stolen, and covers injury or
property damage your vehicle causes to others when at fault. Whether you run a single van or a full
fleet,
it protects your business from the high costs of a road incident — and is required in most states once a
vehicle is used for business.
Commercial Property Insurance
Commercial property insurance protects the physical assets your business depends on — your building,
equipment, fixtures, furniture, and stored inventory — against events such as fire, explosion,
lightning, storms, and theft. If disaster strikes, it provides the funds to repair or replace so you can
resume operations.
It's essential for any business that owns premises or holds significant physical property,
filling gaps that liability and workers' compensation policies do not cover.
Workers' Compensation & DBL
Workers' compensation covers medical costs, rehabilitation, and lost wages when an employee is injured
or becomes ill because of their job, and it protects your business from related lawsuits. Disability
Benefits Law (DBL) is a New York statutory coverage that provides partial wage replacement when an
employee is disabled by an off-the-job injury or illness, including pregnancy.
Together they meet New York's mandatory coverage requirements and keep your team supported both on and
off the clock.
Excess Liability Insurance
Commercial umbrella (excess liability) insurance adds an extra layer of protection that activates once
an
underlying policy — such as general liability, commercial auto, or employer's liability — reaches its
limit. Umbrella coverage can extend several underlying policies at once, while excess liability
typically
extends one.
When a major claim or lawsuit exceeds your standard limits, it steps in to protect the business from a
loss
that could otherwise threaten its survival.