Homeowner's Insurance

Homeowner's insurance protects your owner-occupied home, belongings, and personal liability against events such as fire, theft, storms, and vandalism. It also covers you if someone is injured on your property or you accidentally cause damage to others, and it helps pay living expenses if you're displaced during covered repairs. It protects one of your most valuable assets and is typically required by mortgage lenders.

Landlord's Insurance

Landlord's insurance is for property you rent out to tenants. It covers the building structure, liability tied to the rental premises, and loss of rental income when a covered event makes the unit uninhabitable. Because renting carries added risk, it provides protections a standard home policy does not. Note that it does not cover a tenant's own belongings — those are the tenant's responsibility.

Tenant / Renter's Insurance

Renter's insurance is for those who rent their home. It covers your personal belongings against events such as fire, theft, and water damage, and includes liability protection if you injure someone or accidentally damage the property. It can also help with temporary living costs if your rental becomes uninhabitable. The building itself is the landlord's responsibility — this policy protects what's inside and you.

Vacancy Insurance

Vacancy insurance covers a home left unoccupied for an extended period — often 30 to 60 days or more — when standard home and landlord policies limit or exclude coverage. Empty properties face raised risks, so this policy protects the structure against vandalism, theft, fire, and water damage, and includes liability if someone is injured on the vacant premises. It's ideal for homes between tenants, awaiting sale, or seasonally unoccupied.

Renovation Insurance

Renovation insurance covers a property undergoing significant renovation or construction — a situation standard home policies typically exclude. It protects the structure and building materials against damage from perils such as fire, theft, and weather, and includes liability for injuries that occur on the work site. It safeguards your investment throughout the vulnerable renovation period, until the property is complete and ready for use.

Compulsory Insurance

Building commercial insurance can provide corresponding compensation for the property of an enterprise in case of incidents such as fire, explosion, or lightning strike. This includes but is not limited to: equipment, warehouse storage, buildings, etc.

Full Coverage Insurance

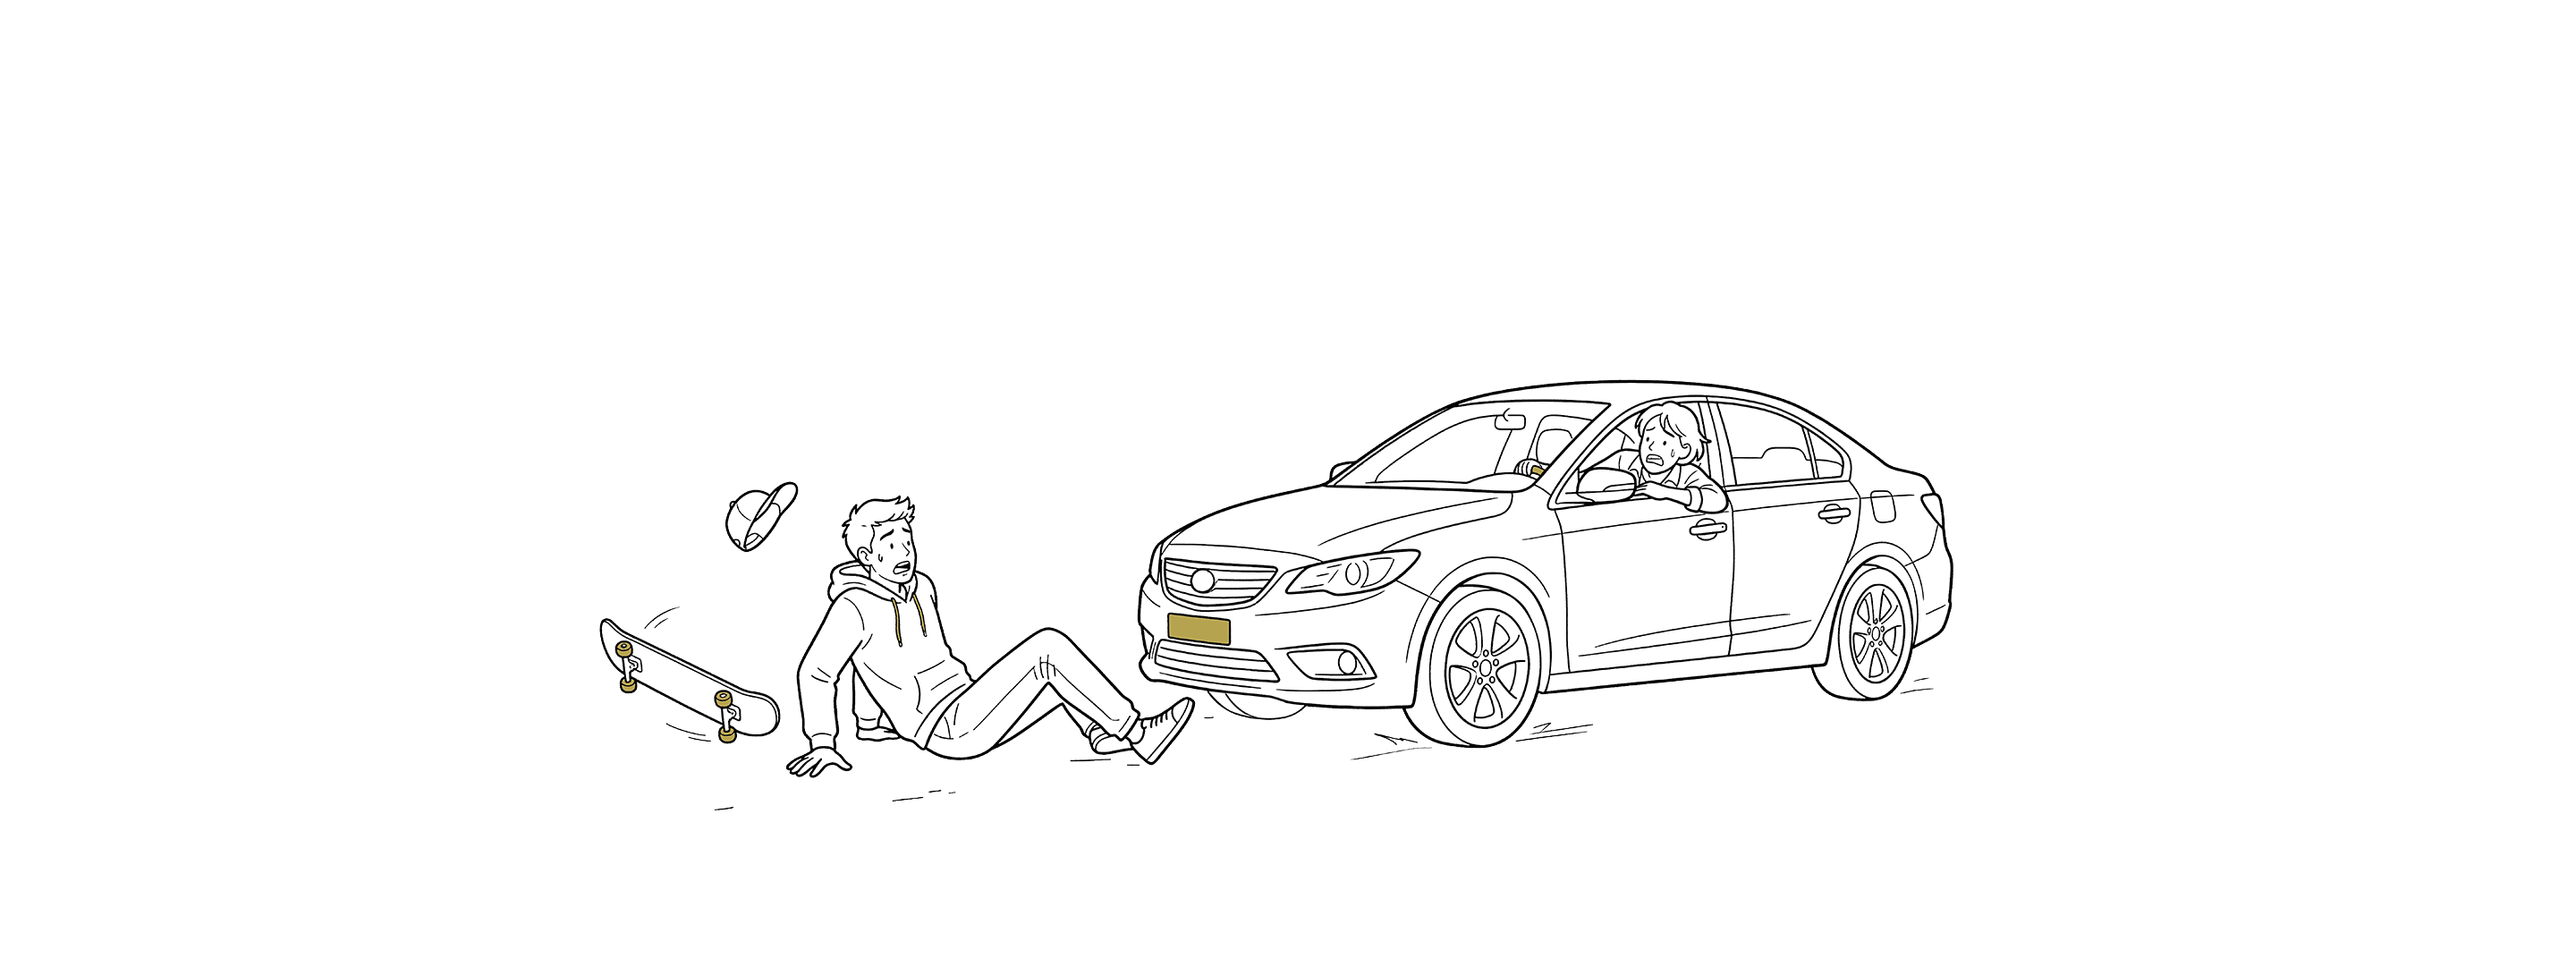
Full coverage insurance combines liability with collision and comprehensive protection. Collision pays to repair or replace your vehicle after an accident, whether or not you're at fault. Comprehensive covers non-collision losses such as theft, vandalism, weather, and hitting an animal. It gives you far broader protection than liability alone, and is usually required by lenders on financed or leased vehicles.

Umbrella Insurance

Umbrella insurance adds an extra layer of liability protection that extends beyond the limits of your home and auto policies, and can extend several underlying policies at once. If a serious accident or lawsuit produces claims larger than your standard coverage can handle, it steps in to protect your savings, home, and other personal assets — an affordable safeguard against the rare but financially devastating event.

We’re here to help
Get In Touch With Us

Share your question*

How can we contact you*

SUBMIT

If you need help, please feel
free to contact us at any time

Please enter your contact information‌险
BACK

We have received your feedback! We will
reply to you as soon as possible!

Copyright © 2026 Verge Group.

Scroll to View

· 中文